Get Started with DSCR Fairway Home Mortgage · Eden Prairie
For real estate agents · First investment property

Your first investment property, qualified on the rent.

You already own your home. You already know what a duplex rents for. A DSCR loan lets the property's cash flow do the qualifying — not your commission history, not your tax returns. Here's how it works and how to start.

Rent ÷ paymentThe only ratio that matters
1–4 unitsSingle-family to fourplex
#1Fairway LO nationwide, 2025
ZeroData collected on this site
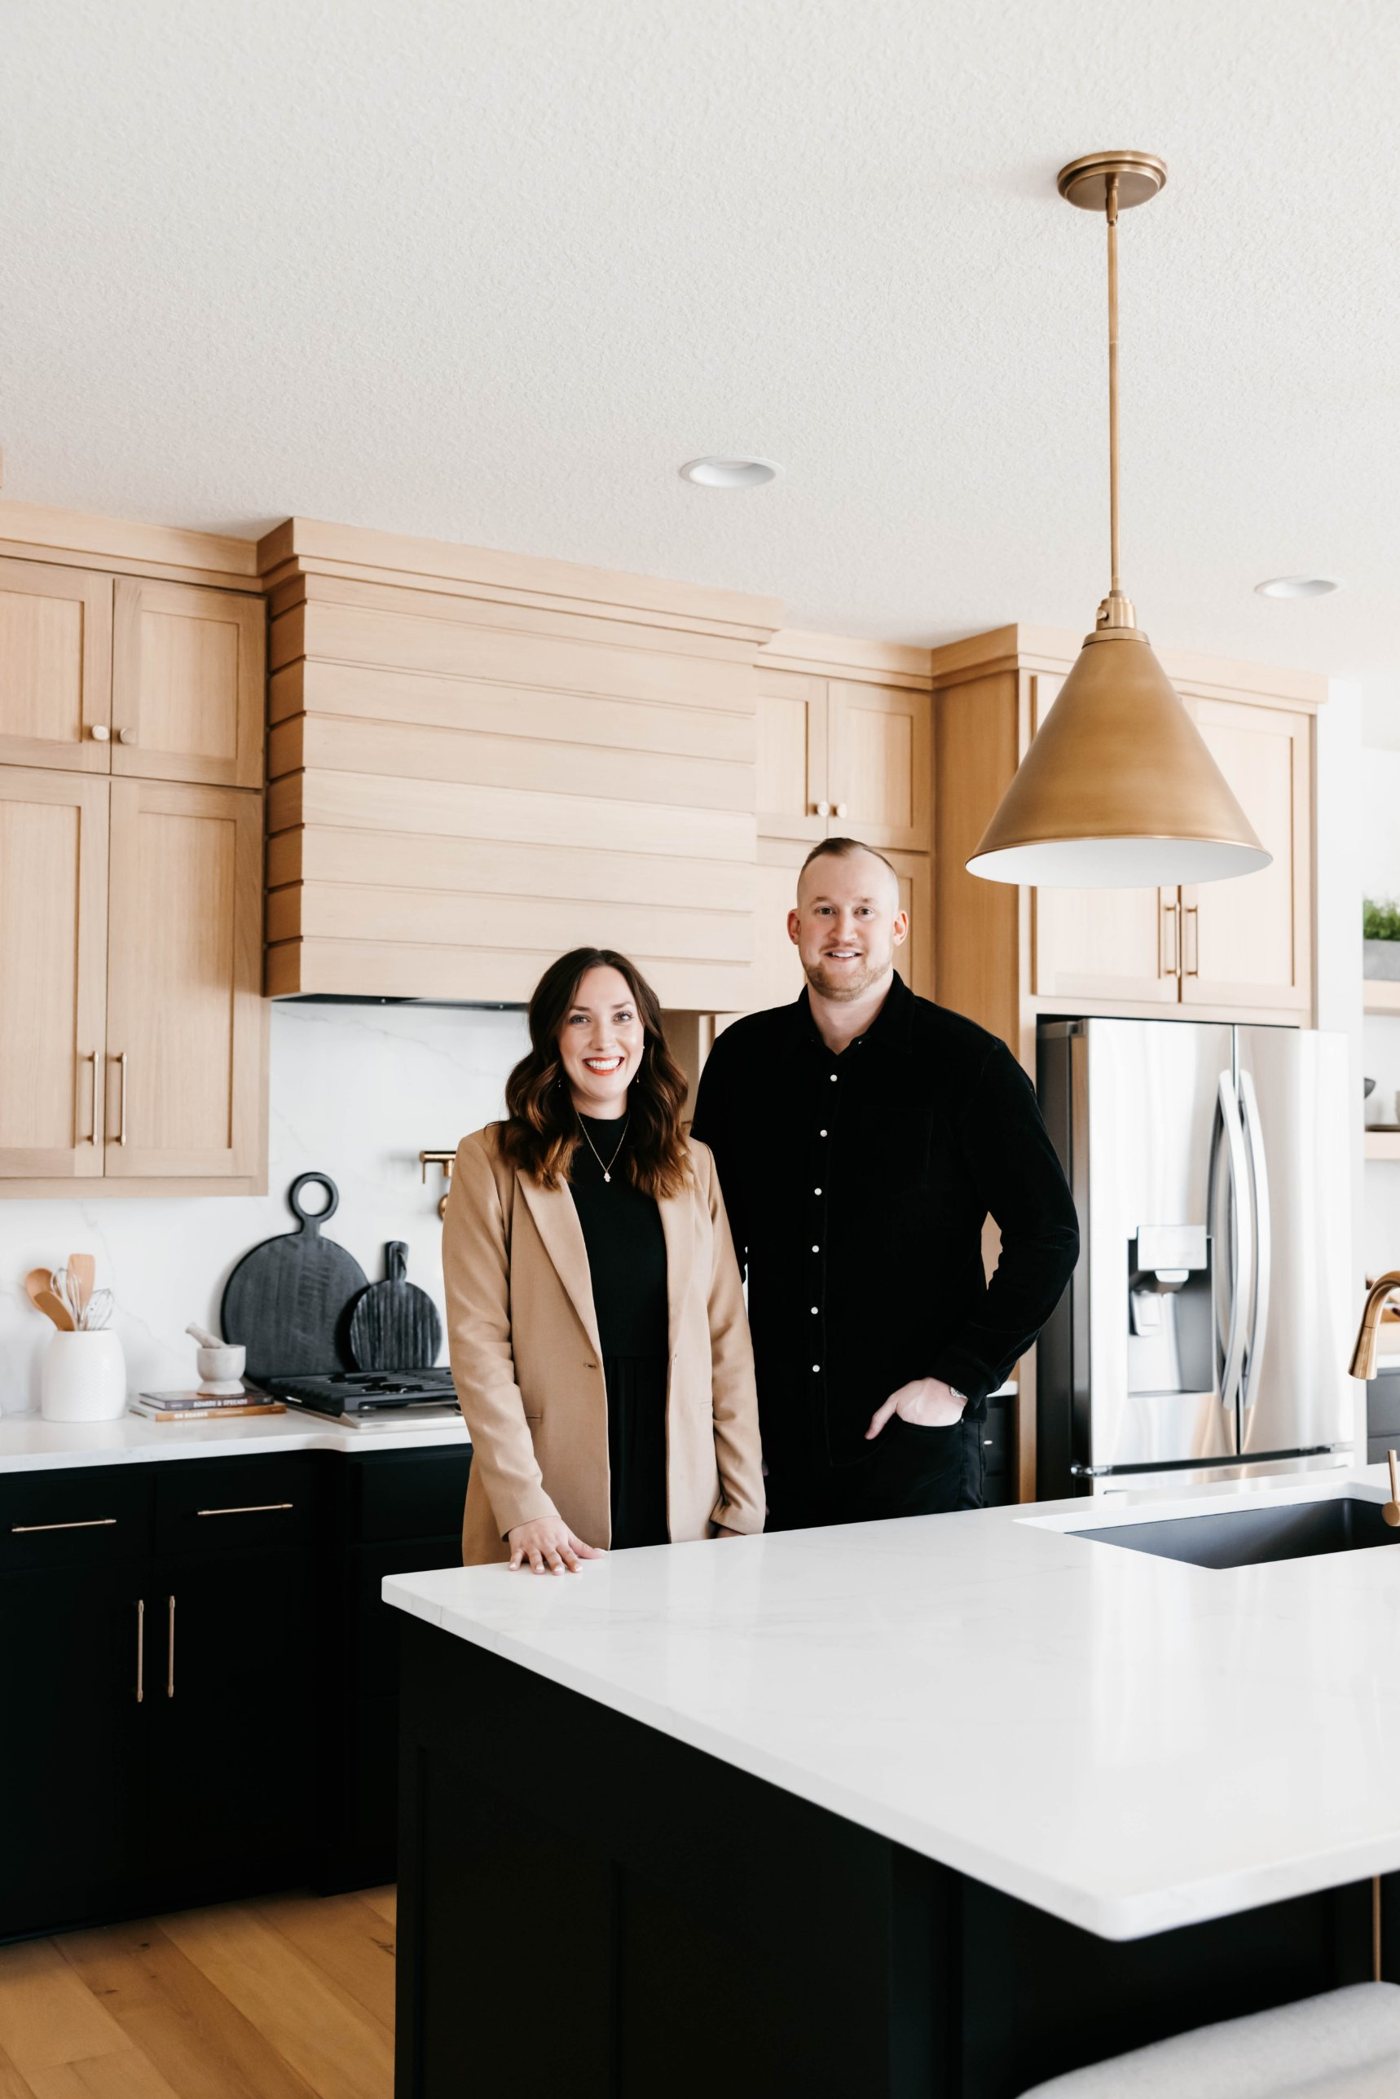
Mercedes Forslund and Oliver White of Fairway Home Mortgage, Eden Prairie
Mercedes Forslund & Oliver WhiteYour connection · Your loan officer, NMLS #1254113
What is DSCR

The loan that looks at the property, not at you

Most agents have never applied for a loan that didn't start with "send me your last two years of tax returns." DSCR starts somewhere else entirely.

One ratio decides it

DSCR stands for Debt Service Coverage Ratio: the property's monthly rent divided by its full monthly payment (principal, interest, taxes, insurance and any HOA). At 1.0 the rent covers the payment exactly. Above 1.0 it covers it with room to spare.
The rent is the income

The lender qualifies the deal on what the property earns, documented by a lease or the appraiser's market-rent analysis. Your personal debt-to-income ratio, your commission history and your tax returns are typically not part of the equation.

Built for investors

DSCR loans are business-purpose loans for 1–4 unit rental properties. Most programs allow the property to be held in an LLC, and the same structure works for the second and third door as well as the first.

Why agents

You're already the best-positioned first-time investor in the room

Every advantage you give your clients, you have too. DSCR is the financing that finally lets you use it.

You see the deals first

You are already touring the duplex before it hits the portals, and you already know which side of town rents in a week.

You know what it rents for

Market rent is the number that drives a DSCR loan. You can estimate it more accurately than almost any other first-time investor.

Your income is the hard part — for other loans

Commission income is lumpy and heavily written off. DSCR sidesteps that entirely by qualifying on the property instead of on you.

You already own your home

Owning your primary residence is a strong starting point. The equity you have built may be one option for the down payment — that is a conversation to have with Oliver, not a promise.

Calculator

Run the numbers on any listing

Type in the rent and the costs. The ratio updates as you go. Nothing you enter leaves your browser — there is no form here, just math.

The property Your numbers

$
$
$
%
yrs
$
$
$

We don't publish rates or minimum down payments on this page — they change, and yours depends on the property and your credit. Call Oliver for the real figures, then type them in here.

Debt service coverage ratio

—DSCR
Enter the numbers
  • Loan amount—
  • Principal & interest—
  • Taxes—
  • Insurance—
  • HOA—
  • Total monthly payment—
  • Monthly rent—

Fill in rent, price, down payment, rate and term to see the ratio.

The calculator is an educational tool. It uses only the numbers you type, stores nothing, and produces an estimate — not a quote, pre-qualification, approval or commitment to lend. Actual qualifying rent, payment, taxes, insurance and program thresholds are determined at application. For real numbers, talk to Oliver.

How it works

Three steps. No forms. No homework before the first call.

01

Text Mercedes

Tell her you want to talk about buying your first rental with DSCR. That is the whole message. She gets you on Oliver's calendar, usually within a day or two.

02

Talk numbers with Oliver

A 20-minute call. Oliver walks you through how DSCR works at Fairway, what the property needs to look like, and what a realistic budget is for you — before you start writing offers.

03

Shop with real numbers

You leave with a pre-qualification and a simple rule for screening listings: does the rent cover the payment? Run it in the calculator on this page on every property you consider.

Will it qualify?

What Oliver looks at

The list is short, and most of it is about the property. Here is the shape of a DSCR file in general terms — Oliver fills in the specifics for yours.

  • A 1–4 unit property you intend to rent outSingle-family, duplex, triplex or fourplex. Not a home you will live in.
  • Rent that covers the paymentDocumented by a lease in place or the appraiser's rent schedule. The calculator below shows you the ratio instantly.
  • A larger down payment than your primary residenceInvestment loans require more down than owner-occupied. Oliver will tell you the current minimum for your scenario.
  • Reserves after closingMost programs want to see a few months of payments set aside. Oliver will tell you how many for your scenario.
  • Decent creditDSCR programs are more flexible on income than on credit. Oliver pulls one report and tells you where you stand.
  • Tax returns, W-2s or a DTI calculationTypically not required on a DSCR loan. That is the point.
Mercedes ForslundFairway · Business Development
Hey Mercedes — I've been showing duplexes in Richfield for years and I think I finally want one myself. Does the DSCR thing work for someone whose income is all commission?
That's exactly who it's built for. Getting you on Oliver's calendar — tomorrow at 11 work?
Perfect. Should I pull my tax returns together first?
Oliver here — no need. Bring the address of a duplex you like and what you think it rents for. We'll run the ratio together on the call and I'll give you the real numbers to plug in.
Illustrative conversation · terms depend on your actual scenario
Side by side

DSCR vs. a conventional investment loan

Neither is "better." DSCR trades a somewhat higher cost for a dramatically simpler qualification. Oliver will show you both so you can choose on purpose.

Feature Conventional investment loan DSCR loan
Who qualifies You — your income, debts and tax returns The property — its rent versus its payment
Income documentation Two years of returns, W-2s, pay stubs A lease or appraiser rent schedule; typically no personal income docs
Commission income Averaged over 24 months, after write-offs Typically not reviewed
Vesting Usually in your personal name Personal name or LLC on most programs
Number of financed properties Capped by agency rules Program-specific; often more flexible
Cost Typically lower rate Typically a higher rate — the trade for flexibility
Prepayment penalty None Common; options vary — ask Oliver
The team

Who's on the other end of the text

Mercedes Forslund

Your connection

Mercedes Forslund

Business Development Manager for the Oliver White Mortgage Group. Mercedes is the person who sent you this page and the fastest way to reach the team — she gets you on Oliver's calendar and keeps things moving. She is not a loan officer and does not discuss loan terms.

Oliver White

Your loan officer · NMLS #1254113

Oliver White

Branch Manager · Loan Officer, Fairway Home Mortgage, Eden Prairie. Oliver personally handles every DSCR conversation and originates the loan. Licensed in Minnesota, Wisconsin, Iowa, North Dakota, Illinois, Arizona, California & Florida.

  • Fairway's #1 individual loan officer nationwide, 2025
  • #1 loan officer in Minnesota by volume, 2025
  • Top 1% Mortgage Originator in America, Mortgage Executive Magazine, every year since 2019
FAQ

The questions agents ask first

What does DSCR actually stand for, and what number do I need?

Debt Service Coverage Ratio — the property's gross monthly rent divided by its total monthly payment (principal, interest, taxes, insurance and HOA). A ratio of 1.0 means the rent exactly covers the payment. Many programs want to see at least 1.0, and a stronger ratio generally means better terms. Oliver will tell you the threshold that applies to your scenario.

Do I really not need tax returns?

On a true DSCR loan, personal income documentation is typically not required — the property's rental income is what gets underwritten. You will still provide the normal asset, credit, identity and property documentation, and the lender will verify the rent with a lease or the appraiser's market-rent analysis.

Can I buy the property in my LLC?

Most DSCR programs allow vesting in an LLC, which is one reason investors choose them over conventional investment loans. Whether that is right for you is a question for your attorney and tax advisor; whether it works for the loan is a question for Oliver.

How much do I need to put down?

More than you would on a primary residence — investment property financing always requires a larger down payment. The exact minimum depends on the program, your credit and the property's DSCR, so we do not publish a number here. Oliver will give you the real figure on your first call.

Can I use the equity in my current home?

Sometimes. Equity from your primary residence is one potential source of down-payment funds, and Oliver can walk you through whether and how that fits. It is a strategy discussion, not a given — and it is one more reason to have the conversation before you start shopping.

Does this work for short-term rentals like Airbnb?

Some DSCR programs allow short-term rental income to be considered and some do not, and the way rent is documented differs. Tell Oliver up front if the plan is a short-term rental so he can point you to the right program.

Is a DSCR loan more expensive than a conventional loan?

Typically, yes — the rate is usually higher than a conventional investment loan, and many DSCR loans carry a prepayment penalty for the first few years. That is the trade for not documenting personal income. Oliver will lay out the actual cost next to a conventional option so you can decide with both numbers in front of you.

I'm an agent — can I represent myself on the purchase?

Usually, yes, subject to your brokerage's policy and standard disclosures. Lending-wise, Oliver will tell you how any commission you earn on your own purchase can or cannot be applied to the transaction.

Do I send documents through this site?

Never. This site collects nothing — no forms, no analytics, no cookies. After you text or email Mercedes, Oliver's team sends a secure Fairway link for the application and any documents.

Who is actually originating the loan?

Oliver White, NMLS #1254113, Branch Manager at Fairway Home Mortgage in Eden Prairie. Mercedes is the fastest way to reach the team; Oliver is the licensed loan officer who quotes your terms and originates the loan.

Door number one

You've helped a hundred people buy a house. Buy the next one for yourself.

One text to Mercedes, one call with Oliver, and you'll know exactly what your first rental needs to look like.

Already know you're ready? Start Oliver's secure Fairway application.